BANKING & PAYMENTS · PAYMENTS & E-MONEY
Payment Service Provider
Framework
Payment initiation, acquiring, and account information are separate permissions with separate liability, and most applications fail on scope rather than substance. We define the scope precisely, then build to it — licence application and safeguarding, connectivity to schemes and banking partners, merchant or platform onboarding, fraud and chargeback controls, and settlement reconciliation.
THE SPECIFICATION
Architecture & Audience
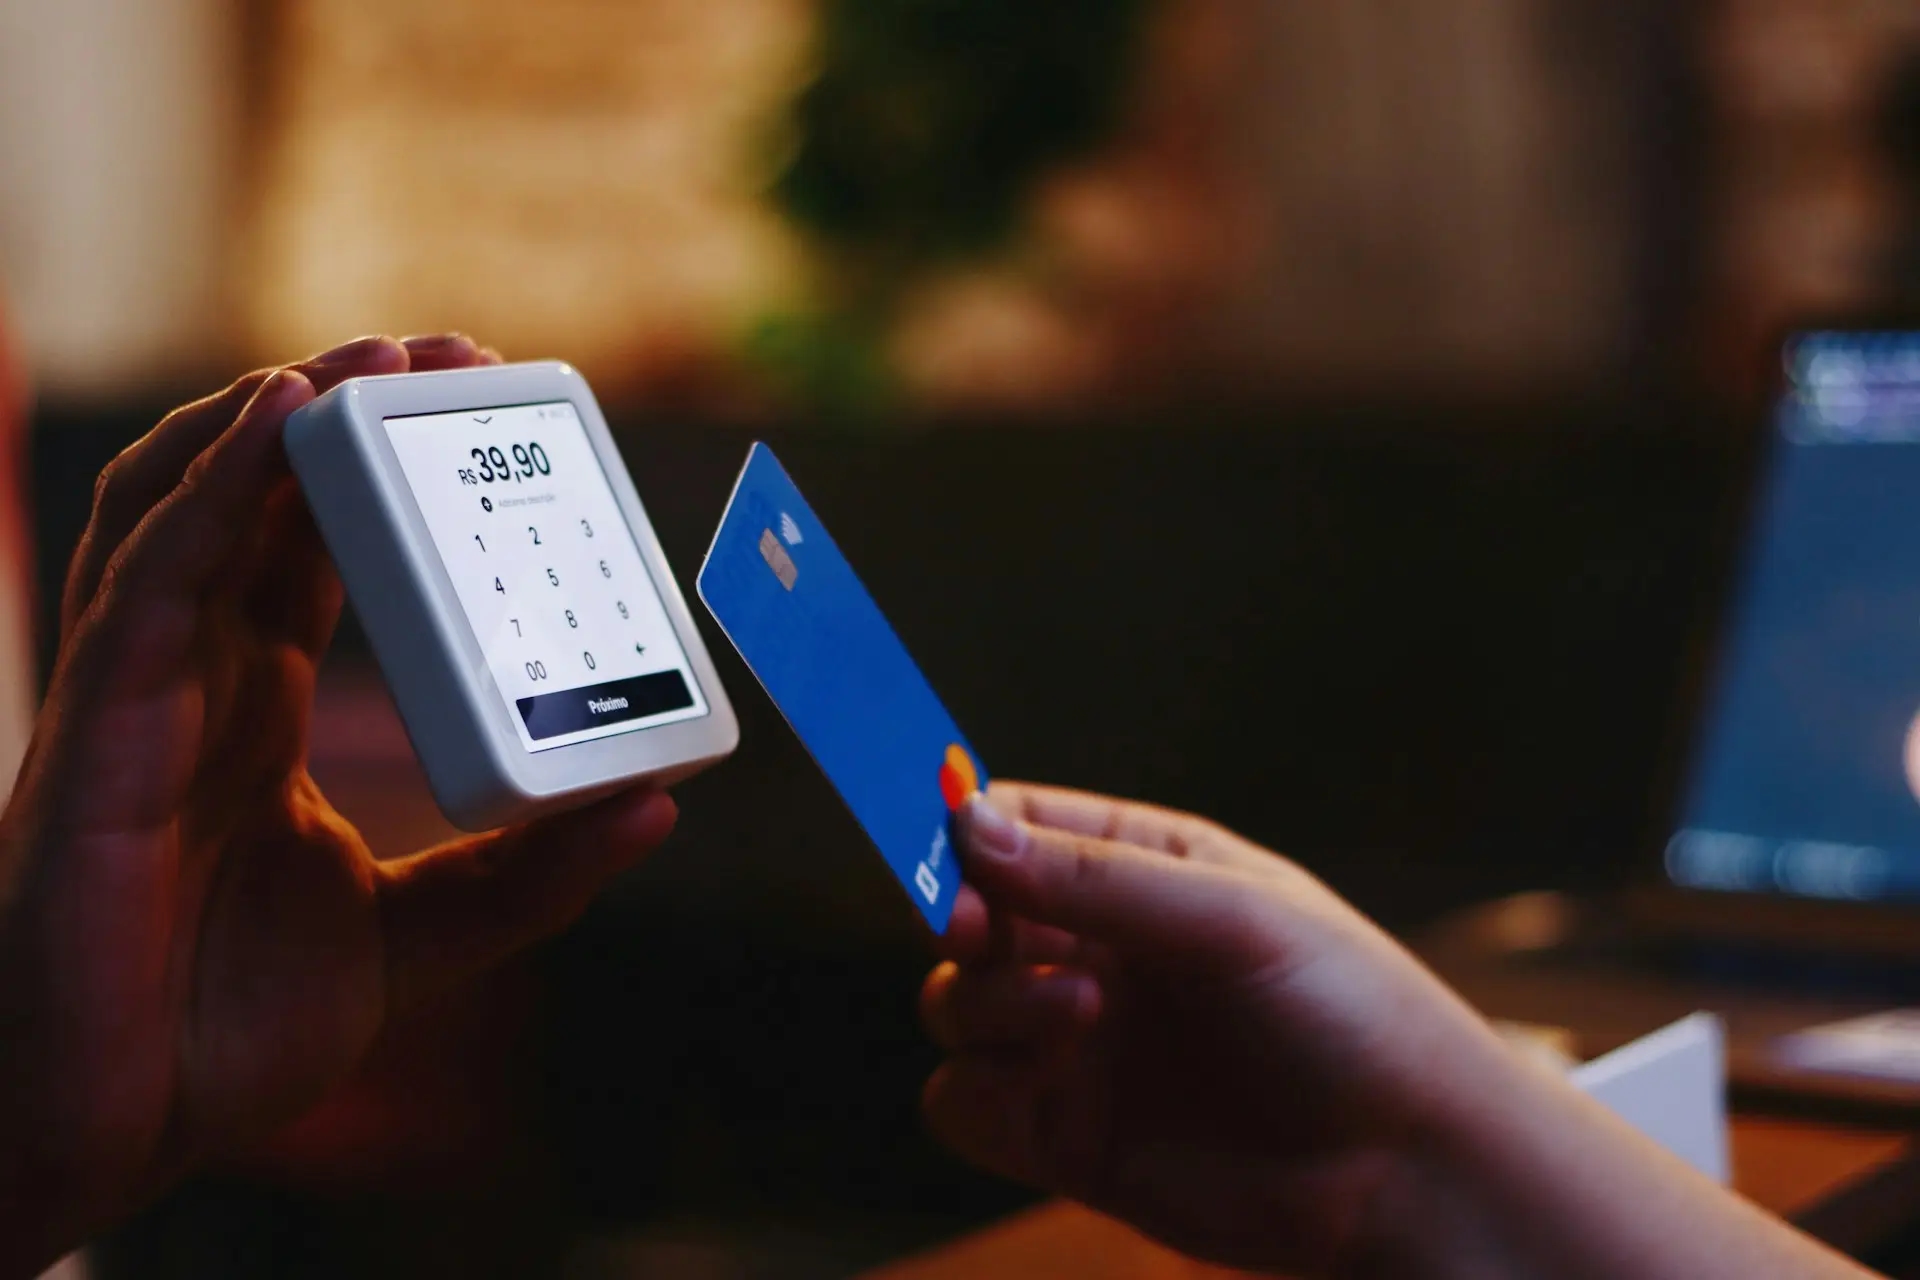
A payment service provider sits in the flow rather than at the destination. It initiates payments, acquires transactions for merchants, or accesses account data on a customer’s instruction — and in most models never holds client funds at all, which lightens the regulatory burden considerably. What it does hold is operational risk: a payment that fails is a payment someone must account for.
Founders building payment infrastructure for a defined merchant segment; platforms monetizing payment flow already passing through them; and technology firms formalizing an unregulated payments function.
What We Deliver
A complete architecture, designed, launched, and managed
We define precisely which payment service permissions the institution requires — initiation, acquiring, account information, or a combination — before any application is filed. Scope determines liability and capital; most applications fail because scope was left too broad or too narrow.
We select and implement the payment gateway and processing infrastructure that handles the transaction volume, payment methods, and currency mix the PSP will process. Infrastructure is selected for reliability and total cost, not vendor relationships.
We negotiate and establish the scheme membership or bank sponsorship arrangements that give the PSP access to the card networks and banking rails it needs. Sponsorship terms are negotiated to reflect the institution’s risk profile, not accepted at the sponsor’s default rate.
We design the settlement architecture that moves funds between the PSP, its banking partners, and its merchants or clients accurately and on schedule. Reconciliation is automated and exception-driven, not rebuilt daily from raw transaction files.
We build the merchant onboarding process and risk framework that screens merchants, sets risk limits, and monitors the portfolio against chargeback and fraud thresholds. The framework is designed to satisfy scheme standards and the PSP’s own sponsor bank.
We implement the financial crime monitoring calibrated to the payment flows the PSP processes: transaction pattern monitoring, sanctions screening on payment instructions, and a SAR filing function that demonstrates the controls work to both the regulator and the sponsor bank.
We build the dispute and chargeback handling function: scheme-compliant response processes, evidence standards, representment procedures, and the management information the compliance function needs to track chargeback rates before they trigger scheme action.
We manage the regulatory approval process for the PSP’s senior management and key function holders. Submissions are prepared to the standard the supervisory authority expects and supported by documentation that demonstrates the governance structure is genuine.
We build the reporting infrastructure that delivers the regulatory submissions required by the PSP’s jurisdiction and the settlement reporting required by its banking partners. Both are produced from the same data source and reconciled before filing.
What We Deliver
A complete architecture, designed, launched, and managed
We define precisely which payment service permissions the institution requires — initiation, acquiring, account information, or a combination — before any application is filed. Scope determines liability and capital; most applications fail because scope was left too broad or too narrow.
We select and implement the payment gateway and processing infrastructure that handles the transaction volume, payment methods, and currency mix the PSP will process. Infrastructure is selected for reliability and total cost, not vendor relationships.
We negotiate and establish the scheme membership or bank sponsorship arrangements that give the PSP access to the card networks and banking rails it needs. Sponsorship terms are negotiated to reflect the institution’s risk profile, not accepted at the sponsor’s default rate.
We design the settlement architecture that moves funds between the PSP, its banking partners, and its merchants or clients accurately and on schedule. Reconciliation is automated and exception-driven, not rebuilt daily from raw transaction files.
We build the merchant onboarding process and risk framework that screens merchants, sets risk limits, and monitors the portfolio against chargeback and fraud thresholds. The framework is designed to satisfy scheme standards and the PSP’s own sponsor bank.
We implement the financial crime monitoring calibrated to the payment flows the PSP processes: transaction pattern monitoring, sanctions screening on payment instructions, and a SAR filing function that demonstrates the controls work to both the regulator and the sponsor bank.
We build the dispute and chargeback handling function: scheme-compliant response processes, evidence standards, representment procedures, and the management information the compliance function needs to track chargeback rates before they trigger scheme action.
We manage the regulatory approval process for the PSP’s senior management and key function holders. Submissions are prepared to the standard the supervisory authority expects and supported by documentation that demonstrates the governance structure is genuine.
We build the reporting infrastructure that delivers the regulatory submissions required by the PSP’s jurisdiction and the settlement reporting required by its banking partners. Both are produced from the same data source and reconciled before filing.
Infrastructure Selection
X-CHASE holds no commercial interest in any provider, assessing them strictly on live performance, structural fit, and renewal terms. Providers are named exclusively under formal engagement, never on a public website.