A R C H I T E C T U R E · D O C T R I N E · STUDY NO. 04
The Trading Imperative
On why the modern bank must build its own trading and asset management division, the evidence from the apex, the acquisitions that prove the thesis, the widening technical gap between the leaders and the rest, and the infrastructure that makes the crossing possible.
A R C H I T E C T U R E · D O C T R I N E
STUDY NO. 04
Abstract
A bank that only lends has chosen to earn the smallest return available on the largest privilege in finance. The commercial bank holds a position no other institution can replicate: a captive base of deposits, a regulated balance sheet, direct access to central.
bank money, and the trust of clients who already route their financial lives through its rails. Yet the majority of the world’s banks convert this position into a single, narrow revenue stream — the interest margin — while the institutions at the apex of the industry have spent two decades converting the same position into something far larger: markets divisions that trade, make prices, execute for clients, manage assets, and generate tens of billions of dollars in revenue that no rate cycle can take away.
This study argues a single thesis: the trading division is no longer a specialty of Wall Street; it is a structural requirement of the modern bank. The evidence sits in three places — in the earnings of the American giants, in the acquisition record of the world’s most conservative private banks, and in the growing infrastructure market that now allows any sufficiently governed institution to reach the interbank floor directly. The banks that build will compound. The banks that wait will watch their deposits fund someone else’s trading desk.
D E F I N I T I O N · T H E T W O B A N K S
The lending bank earns the spread between what it pays for deposits and what it charges for loans — an income set by the central bank’s rate cycle, not by the bank itself. The trading bank earns from flow: execution, market-making, brokerage, custody, and asset management — an income set by client activity, which persists in every regime. The first is a passenger of monetary policy. The second is a participant in the market.
E X H I B I T · T H E C O U R S E O F T H E S T U D Y
- IThe Balance Sheet That SleepsThe largest privilege in finance, working at half its weight.
- IIThe Anatomy of the DivisionFour connected businesses, one architecture.
- IIIThe Evidence of the ApexThe record quarters, and what they preview
- IVThe AcquirersWhen the most conservative money buys brokers
- VThe Consultancy RecordThe price the market puts on rented income.
- VIThe Gap and the OpeningThe concentration of flow — and the late mover’s advantage
- VIIThe EnablersThe infrastructure that now makes the crossing possible.
- VIIIStrategic RealitiesSeven facts the board cannot delegate
- IXThe DoctrineThe second half of the bank.
The Balance Sheet That Sleeps
Consider what a mid-sized commercial bank actually is, stripped of its branding: a licensed warehouse of client money, connected to the national payment system, staffed to assess risk, and regulated to hold capital against it. Every component of a trading operation is.
already present in embryo — the funding, the custody, the client relationships, the risk function, the regulatory standing. What is absent is not capability. It is architecture.
The cost of that absence is measured in dependence. A bank whose revenue is dominated by net interest income has outsourced its profitability to the rate-setting committee of its central bank. When rates rise, it prospers without effort; when rates fall, it suffers without recourse.
This is not a business model. It is a weather pattern with a balance sheet. The consultancies have begun to say this plainly.
Deloitte’s 2026 outlook for the industry notes that strong, diversified noninterest income should continue to be the key revenue driver for banks in 2026, with investment banking and capital markets set for growth — a polite way of stating that the interest margin can no longer carry the institution alone. The deposit is the privilege. The trading division is what the privilege is for.
E X H I B I T · T H E T W O I N C O M E S
| THE INTEREST MARGIN | THE FLOW REVENUE | |
|---|---|---|
| Set by | The central bank’s rate cycle. | The client’s own activity |
| Behavior in volatility | Punished — through credit risk. | Paid — through turnover. |
| The market’s verdict | Discounted, as income that is rented. | Capitalized, as income that is owned. |
| Within the bank’s control | No — it is monetary weather. | Entirely — it is built, or it is exported. |
Source: SOURCE : X-CHASE · OF F ICE OF INST I TUT IONAL INT E L L IGENCE (HOUSE FRAMEWORK)
A deposit that only funds a loan is capital working at half its weight.
The Anatomy of the Division
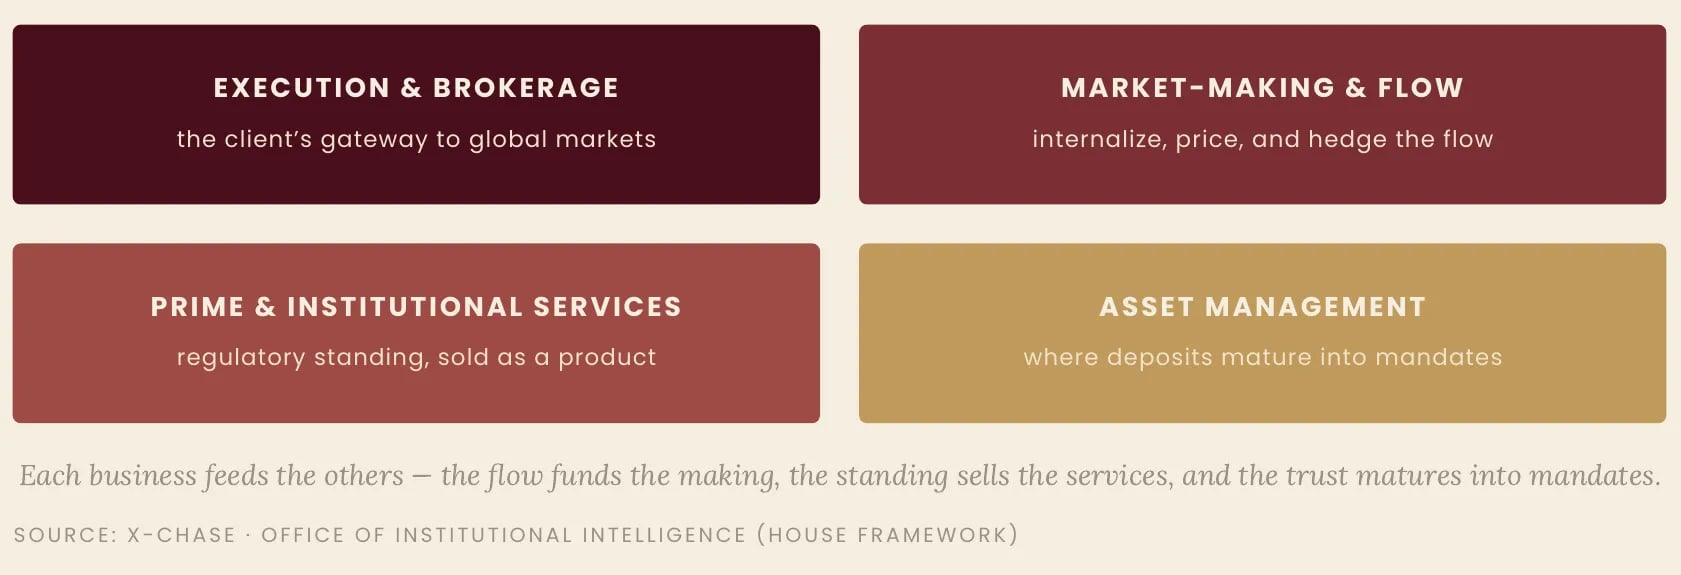
Before the evidence, the definition. A bank’s trading and markets division, properly built, is not a speculative desk gambling the balance sheet. It is a portfolio of four connected businesses, each feeding the others.
The first is execution and brokerage — giving the bank’s retail and institutional clients direct access to global markets through the bank’s own platform, under the bank’s own brand, on the bank’s own terms. Every client who today leaves the bank to open an account at a foreign broker is revenue exported. The second is market-making and flow trading — internalizing that client flow, pricing it, hedging it, and capturing the spread that currently accrues to an external intermediary. The third is prime and institutional services — extending credit, custody, and clearing to smaller financial institutions, funds, and family offices in the bank’s region, converting the bank’s regulatory standing into a product. The fourth is asset management — the natural destination of client trust, where deposits mature into mandates.
None of these four requires the bank to build technology. All four require the bank to build structure — governance, risk architecture, vendor selection, and the operating discipline to run a markets business inside a banking institution. That distinction, between building software and building an institution, is the subject of Section VII.
Exhibit · The Four Businesses of the Division
A bank sells its trust once when it writes a loan; a markets division sells the same trust a thousand times a day.
The Evidence of the Apex
The American banks are not a benchmark. They are a preview. What their earnings show is not what an exceptional bank can do — it is what the banking business becomes when the trading division is treated as a core organ rather than an appendix.
The current numbers are without precedent. In the second quarter of 2026, JPMorgan Chase generated $6 billion in equities revenue — an 86% jump year over year — alongside $6.1 billion in fixed income, bringing total markets revenue to $12.1 billion in a single quarter. Morgan Stanley reported record equity trading revenue of $6.3 billion, up 69%. Bank of America posted record equities revenue of $3.6 billion, up 70%, with FICC adding $3.5 billion. Citigroup’s equities business climbed 45% to a record $2.3 billion. Across the industry, banks were projected by BCG Expand to generate a record $169 billion of global markets revenues in the first half of 2026 alone — 16% above the prior year, which was itself the highest client-facing market-making revenue total in history.
Exhibit · Record Equities Revenue — Second Quarter 2026
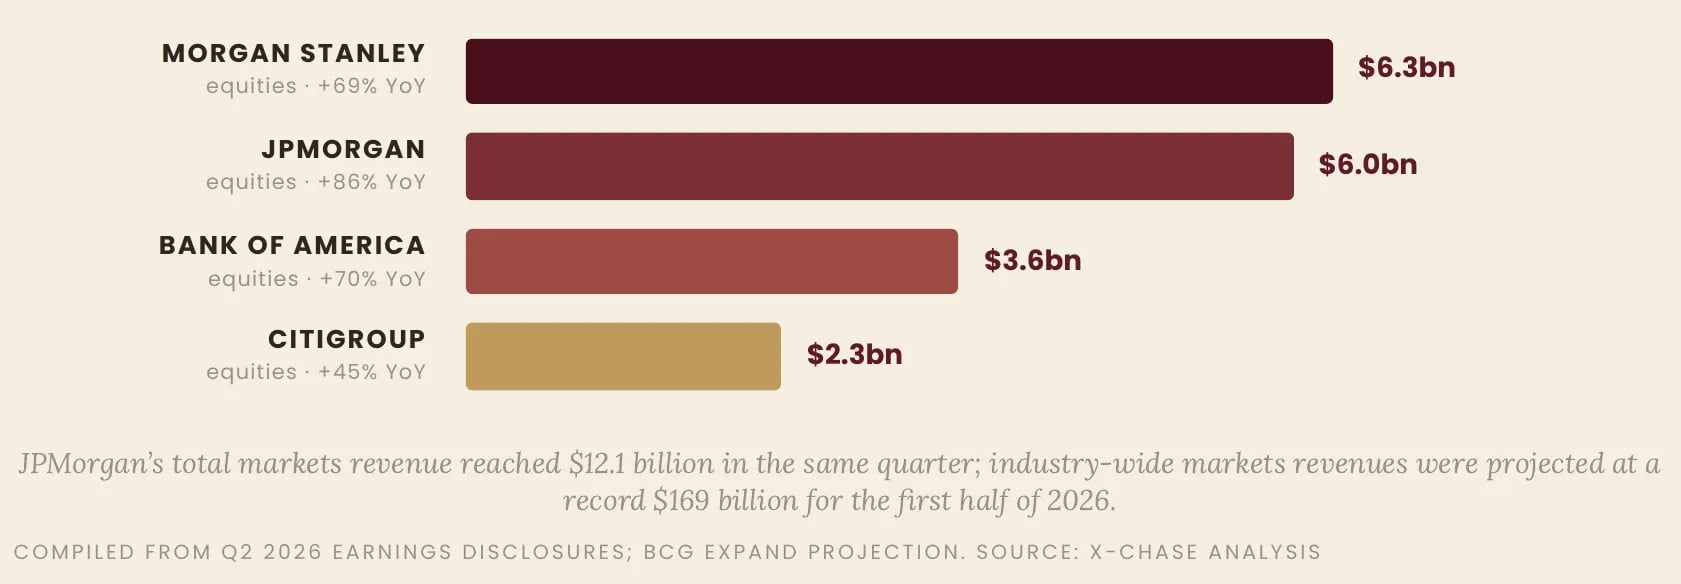
Read those figures against the structure of an ordinary commercial bank and the strategic point becomes unavoidable. These are not proprietary gambling profits; they are predominantly client-facing revenues — execution, intermediation, financing — earned from flow that exists because clients need to trade. The flow exists in every country. In most countries, the local banks have simply declined to capture it, and it is captured instead by foreign institutions and offshore brokers.
There is a second lesson inside the numbers: the revenue is durable across regimes. Since 2020, a period of structurally greater volatility has meant structurally higher markets revenues for the global banks — a now familiar pattern of records falling year after year. Volatility, which punishes the lending bank through credit risk, pays the trading bank through activity. A bank with both businesses is hedged against its own century.
What the apex earns from flow, the base pays in absence.
The Acquirers — When Banks Buy Brokers
If the thesis were merely theoretical, it could be debated. But the most conservative institutions in world banking have already voted — with capital.
The defining transaction is recent and instructive. In March 2025, J. Safra Sarasin — a family-owned Swiss private banking group of the old school, an institution whose entire brand is discretion and multi-generational caution — announced the acquisition of approximately 70% of Saxo Bank, the Danish trading and investment bank, a stake worth slightly over €1.6 billion. The transaction completed in March 2026 with the approval of both the Swiss and Danish regulators, creating a combined group with over $460 billion in client assets, with Saxo’s founder Kim Fournais retaining 28% and moving to chairman. Consider what was purchased: not deposits, not branches, not a loan book — a trading platform, a technology-driven brokerage with a banking license. The Swiss group stated its intention plainly: it intends to integrate Saxo’s technology platform, and Saxo will deepen its business-as-a-service partnerships with banks, corporates, family offices, and asset managers. One of Europe’s most guarded private banks concluded that the future of wealth management runs through trading infrastructure — and paid over a billion euros to acquire it rather than remain without it.
The American precedent came five years earlier, and at even greater scale. In 2020, Morgan Stanley acquired the online brokerage E*TRADE for $13 billion — the largest takeover by a U.S. bank since the financial crisis — bringing together $3.1 trillion in client assets, and with it 5.2 million customer accounts and $56 billion in low-cost deposits to fuel the bank’s lending. Note the direction of the logic: the trading platform did not need the bank — the bank needed the trading platform, both for its clients and, remarkably, for its deposits. In the same wave, Charles Schwab completed its $26 billion all-stock purchase of TD Ameritrade, consolidating the American retail brokerage landscape under balance-sheet institutions.
Exhibit · The Acquisition Record
| Consideration | What was purchased | |
|---|---|---|
| Safra Sarasin → Saxo (2025–26) | ≈70% · just over €1.6bn | A multi-asset trading platform with a banking license; a combined group of $460bn+ in client assets. |
| Morgan Stanley → E*TRADE (2020) | $13bn | 5.2 million accounts and $56bn in low-cost deposits — the largest U.S. bank takeover since the crisis. |
| Schwab → TD Ameritrade (2020) | $26bn · all stock | The consolidation of American retail brokerage under balance-sheet institutions. |
Source: Public disclosures; X-CHASE analysis.
The pattern extends across the industry’s most sophisticated tier. Switzerland alone hosts two full banks — Swissquote and Dukascopy — whose core business is online brokerage: licensed banking institutions built around multi-asset trading platforms, proof that the bank-as-broker model is not an American anomaly but a durable institutional architecture. Behind the retail surface, the American giants operate the world’s prime brokerage layer — the credit and clearing infrastructure on which the global brokerage industry itself depends — meaning that even the brokers who appear independent are, at the level of liquidity and credit, extensions of bank trading divisions.
The acquisition record admits one reading: the institutions with the most information about where banking is going are buying trading capability, at premium prices, in cash and stock. They are not diversifying. They are correcting an architecture they have concluded is incomplete.
Exhibit · The Convergence — Banks That Broker, Brokers That Bank
| Jurisdiction | The pattern | |
|---|---|---|
| Swissquote | Switzerland | A licensed bank whose core business is a multi-asset online brokerage. |
| Dukascopy | Switzerland | A banking license built around an electronic trading platform. |
| Saxo · Safra Sarasin | Denmark · Switzerland | A trading platform with a banking license, brought under a private bank’s roof. |
| E*TRADE · Morgan Stanley | United States | The brokerage that brought the bank its clients — and its deposits. |
| TD Ameritrade · Schwab | United States | The broker consolidated into a balance-sheet institution. |
Source: Public disclosures; X-CHASE analysis. The record reads in both directions — banks buying brokers, and brokers maturing into banks. Two roads, converging on the same architecture.
When the most cautious money in banking buys trading platforms, the debate is over; only the timing remains.
The Consultancy Record — The Price of Rented Income
The strategy houses have reached the same conclusion from the opposite direction — not by studying the winners, but by auditing the anxiety of everyone else. And their audit contains a paradox that only one distinction can resolve.
McKinsey’s Global Banking Annual Review describes an industry that is simultaneously triumphant and disbelieved. Global banking revenues before risk costs rose from $6.1 trillion in 2024 to $6.4 trillion in 2025, with profits climbing seven percent to $1.3 trillion — by absolute profit, one of the most lucrative industries on earth. Yet the same industry trades at the lowest price-to-book and price-to-earnings ratios of any sector — roughly 67 percent below the cross-industry average — and even the exceptional results of 2024–25 have closed the gap only slightly. Return on tangible equity has already turned down again, from 12.4 percent in 2024 to 11.8 percent in 2025, and the central scenario, should banks fail to adapt, is an erosion of some $170 billion — nine percent — of global profit pools, as fintechs, private credit firms, and wealth managers carve away the most attractive slices of revenue.
An industry that earns more than almost any other and is valued below all of them is not a puzzle. It is a verdict. The market distinguishes between income a firm owns and income it rents. The interest margin is rented — from the rate cycle, from a committee the bank does not sit on, from a monetary weather system it can neither govern nor forecast — and the market capitalizes rented income at a discount, because rent can be revised without notice. Fee and flow income — execution, markets, wealth — is owned: set by client activity, defended by relationship, present in every regime. This is why the discount does not close in profitable years. The market is not disputing the profits. It is disputing their provenance.
Exhibit · The Valuation Verdict
| Reading | What it says | |
|---|---|---|
| Global revenues · 2025 | $6.4tn, up from $6.1tn | The franchise has never earned more. |
| Global profits · 2025 | $1.3tn · +7% | Among the most profitable industries on earth. |
| Price-to-book | ≈67% below all-industry average | The market does not believe the income is owned. |
| Return on tangible equity | 12.4% → 11.8% | The cycle is already taking back what it lent. |
| Profit pool at risk | ≈$170bn · 9% | The rent notice, served by nonbank competitors. |
Source: Compiled from McKinsey Global Banking Annual Review; X-CHASE analysis.
A bank that wants its multiple repaired therefore holds exactly one lever fully within its own control: change the composition of its revenue — the share that is owned rather than rented. That is not a cost program, and it is not a technology budget. It is the construction of the markets division.
The market has already priced the lending bank’s future. It is waiting to price the trading bank’s.
The Gap and the Opening — The Apex, the Regions, and the Late Mover’s Advantage
Now the uncomfortable section — and, read to its end, the most promising one.
Begin with the geography of the market itself, because the concentration is starker than most bank boards realize. The 2025 BIS Triennial Survey — the definitive census of the world’s largest market — recorded global foreign exchange turnover of $9.6 trillion per day in April 2025, up 28% from $7.5 trillion in 2022. Of that ocean, sales desks in the United Kingdom alone intermediate 37.8% — roughly $3.6 trillion every day — with the United States at 19% ($1.8 trillion), Singapore at 11.8%, and Hong Kong at 7%. A handful of hubs, in other words, capture roughly three-quarters of the daily turnover of the most traded market on earth.
Exhibit · Where the World’s Flow Is Priced — Share of Global FX Intermediation
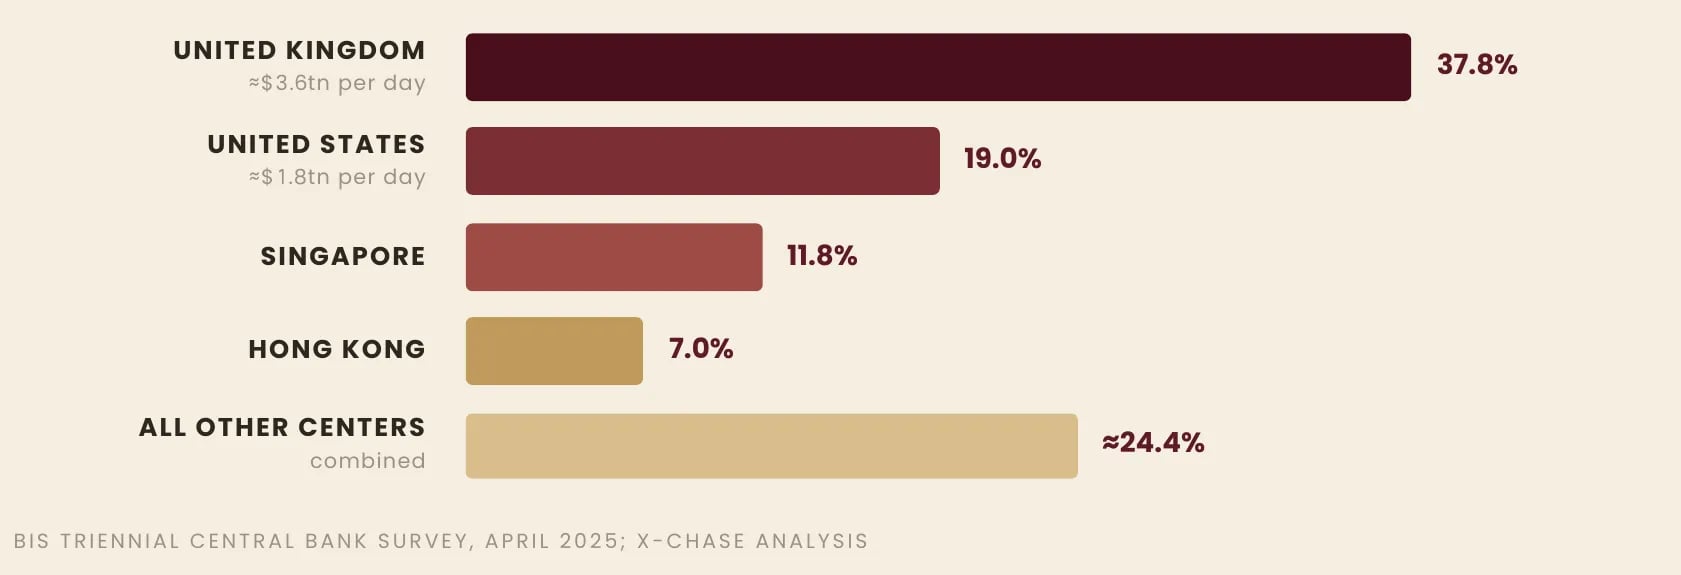
The entire Middle East, for all its capital, its sovereign wealth, and its trading culture, intermediates a share so small it barely registers in the survey — not because the region lacks flow, but because the region’s flow is executed elsewhere, on infrastructure owned by others. Every day, the trading activity of Gulf, Asian, and African clients — retail and institutional alike — is priced in London, cleared in New York, and monetized by institutions that hold no relationship with the client beyond the ticket.
The gap that produces this is not one of capital. Gulf banks in particular are among the best-capitalized institutions on earth, with sovereign backing, pristine balance sheets, and deposit franchises the American banks would envy. The gap is technical, and it runs through every layer of a markets operation. The apex institutions operate co-located execution infrastructure measured in microseconds; algorithmic pricing engines that quote thousands of instruments continuously; real-time, cross-asset risk systems that mark the entire firm to market intraday; and internalization engines that match client flow against client flow before a single order ever leaves the building. The typical regional bank, by contrast, offers its clients equity access to the local exchange through an aging order-routing front end, hedges its treasury exposures by telephone through a correspondent bank in London, and sends any client who asks for global multi-asset access out the door to a foreign platform. The regional bank has become, in effect, the funding department of the international brokerage industry.
But here the analysis must turn, because the same facts that describe the gap also describe the opening — and the regional bank holds three advantages the incumbents cannot buy.
The First Advantage · The Absence of Legacy
The apex banks carry decades of accumulated systems — mainframes wearing modern interfaces, technology estates so layered that, as McKinsey observes, banks spend more on technology as a share of revenue than any other industry, yet productivity gains remain elusive. A bank building its markets division today builds nothing twice: it assembles the current generation of infrastructure directly, the way the Gulf’s telecommunications networks skipped the copper age entirely and arrived at fiber. The late mover pays no demolition costs.
The Second Advantage · Jurisdiction
The financial centers rising fastest in the global architecture — ADGM, DIFC, and their peers — are on the regional bank’s doorstep, actively licensing markets businesses, and competing to host precisely this kind of institution. The regulatory pathway that took the apex banks a century of accretion is available to the regional entrant as a designed, deliberate route.
The Third Advantage · The Client
The flow being exported is not anonymous international flow — it is the regional bank’s own depositors, its own corporate relationships, its own family offices, currently served offshore for want of a domestic alternative. No foreign institution can match the incumbency of the bank that already holds the client’s accounts, the client’s trust, and the client’s jurisdiction. The moment a credible domestic markets capability exists, the repatriation of that flow is not a marketing challenge. It is a homecoming.
The strategic environment, then, is not a verdict on the regional bank. It is a window — open now, and closing at the speed at which the newly licensed institutions next door are building. A regional bank that does not build a markets capability within this decade will not merely miss a revenue line; it will watch better-instrumented entrants intermediate its own clients. One that builds now inherits the most valuable position in the coming architecture: the licensed, capitalized, trusted institution standing closest to the flow.
The pioneers paid for the map. The late mover inherits it — and travels lighter.
The Enablers — The Infrastructure of the Crossing
Here the thesis turns from diagnosis to feasibility — because the single most important structural change of the past decade is this: a bank no longer needs to be JPMorgan to trade like one.
Twenty years ago, the machinery of a markets business was proprietary by necessity. Each apex bank wrote its own pricing engines, wired its own risk, and guarded both as the crown jewels they were. That age has ended. The markets-infrastructure industry has matured into a complete, institutional-grade supply chain, in which every organ of a trading operation — liquidity, aggregation, execution, risk, custody, reporting — is available as licensed, hosted, continuously maintained infrastructure, deployable in months and improved by specialists whose entire business is its excellence. The apex banks themselves now buy half their stack. What was once built is now assembled — and what can be assembled can be assembled by any institution governed well enough to hold it.
Exhibit · The Supply Chain of the Crossing
| The function | The provider class | |
|---|---|---|
| Liquidity & Credit | Direct, credit-intermediated access to interbank pricing across FX, metals, indices, and beyond. | Tier-1 prime brokers; institutions of the LMAX, Sucden Financial, and Invast Global class. |
| Aggregation & Bridging | Price aggregation, smart order routing, and real-time risk across venues. | The Centroid Solutions, PrimeXM, and oneZero class. |
| Trading Platforms | Client-facing execution across retail and institutional channels. | The Devexperts and MetaQuotes class. |
| Core Integration | Connection of the markets stack to the banking core and its ledgers. | The Avaloq and Temenos class. |
| Digital-Asset Custody | Institutional-grade custody and settlement of the newest asset class. | The Fireblocks and Copper class. |
Source: Provider classes are illustrative of the market’s structure, not statements of partnership. X-CHASE · Office of Institutional Intelligence (House Framework).
This changes the nature of the board’s question completely. It is no longer “can we build the technology of a trading division?” — no one builds it anymore. The question is the harder and more interesting one: can we design the institution around it? Which liquidity architecture matches the bank’s client profile and risk appetite; which providers, in which combination, on which terms; what governance separates the client business from the balance sheet; what risk framework, what regulatory pathway, what sequence of launch. The barrier to entry has migrated from technology to institutional design — from code to architecture.
That migration is the entire opportunity. Technology can be procured by anyone with a budget. Architecture — the discipline of binding providers, governance, liquidity, and operations into a single coherent institution — is the scarce capability, and the only one that cannot be licensed.
The machinery of the apex is now for hire. Its architecture is not — that must be designed, and design is where institutions are actually born.
Strategic Realities
Seven facts the board cannot delegate
- IThe interest margin is rented, not owned.A bank whose income is set by the rate cycle has outsourced its profitability to its central bank. Flow revenue — execution, brokerage, market-making, asset management — is the only income a bank sets for itself, and the only kind the equity market rewards with a multiple.
- IIThe flow already exists; only its destination is chosen.A $9.6 trillion daily market does not need to be created — three-quarters of it is simply intermediated by a handful of hubs. The bank’s clients are already trading, through foreign brokers and other institutions’ infrastructure. The trading division does not create demand. It repatriates it.
- IIIThe acquisition record is the proof of concept.Morgan Stanley paid $13 billion for a broker. J. Safra Sarasin paid over €1.6 billion for majority control of another. The most informed and most conservative capital in banking has concluded that trading capability is worth buying at a premium. That conclusion is available to every bank, free of charge.
- IVVolatility taxes the lender and pays the trader.Credit risk rises when markets convulse; markets revenue rises with it. A bank holding both businesses is hedged against every regime. A bank holding only one has chosen a side without knowing it.
- VThe technology barrier has fallen; the design barrier remains.Every component of an institutional markets stack — liquidity, platform, risk, custody, reporting — is now available from best-in-class providers. What cannot be procured is the architecture that binds them into an institution. The scarce input is no longer software. It is design.
- VIThe late mover travels lighter.The regional bank carries no legacy estate to demolish, sits beside jurisdictions competing to license it, and already holds the clients whose flow is being exported. These are advantages the apex cannot purchase — and they depreciate only through delay.
- VIIThe cost of waiting compounds.Every year without a markets division is a year of exported flow, a year of valuation discount, and a year in which the newly licensed institution across the street builds the client relationships the bank assumed were permanent. Structural gaps do not hold still. They widen.
The Doctrine — The Second Half of the Bank
We return to the opening image, now able to state it fully. The bank that only lends is half an institution — the funding half, the custody half, the trust half — operating without the half that converts funding, custody, and trust into participation in the markets its clients already inhabit. For a century, the missing half could be excused: the infrastructure of a markets business was proprietary, the expertise was concentrated in a handful of cities, and the regulators of most jurisdictions had no framework to receive it. None of those excuses survives the present decade. The infrastructure is for hire, the expertise is transferable, and the international financial centers are competing to license precisely this kind of institution.
What remains is the decision — and the discipline. A trading division built badly is a hazard; the history of finance is a museum of banks that speculated where they should have intermediated. The division must be designed: client-facing before proprietary, flow before position, governance before growth, with the risk architecture erected before the first ticket is written. Built this way, it is not a departure from the conservatism of banking but its completion — the conversion of the deposit franchise, the oldest privilege in finance, into its full institutional expression.
The banks of the apex have shown what the completed institution earns. The acquirers have shown what the incomplete institution must eventually pay to become whole. The gap between them is not talent, not capital, not license. It is architecture — and architecture, unlike history, can be commissioned.
The deposit was never the business. It was the permission to build one.